Reverse mortgages Perth
We arrange reverse mortgages in Perth for homeowners aged 55 and over. Before you apply, we show you how much of your home would still be yours, your equity, after 5, 10 and 20 years.
- Borrow against your home from age 55, with no repayments while you live there.
- We compare the lenders that offer reverse mortgages, which is a short list.
- We work out how much of your home is left in 10 and 20 years before you apply.
- Run your own figures on the same method as Moneysmart's calculator.
 21+Years broking

 $1B+Loans settled
 40+Lenders compared
Our awards and recognition
Awarded by the people who see every broker’s numbers
Diamond Club
2026
Money Quest Group
Diamond Club
2025
Money Quest Group
Diamond Club
2024
Money Quest Group
Mortgage Broker of the Year
2023/24, National, highest dollar volume settled
Southern Cross Broker Network
Excellence in Finance, Gold
2021
PLAN Australia
Excellence in Finance, Gold
2020
PLAN Australia
Hall of Fame
Valued partner, 15 years
PLAN Australia
Elite Broker
2021
Broker Value Proposition
Premium Broker
ANZ
Individual Excellence Award
2016
Specialist Finance Group
Sales Excellence Award
PLAN Australia
Sales Master Award
PLAN Australia
Top 100 Brokers
Four times
Australian Broker
What our reverse mortgage service does
The work we do on a reverse mortgage, from the first projection to settlementA reverse mortgage is a loan against your home with no repayments, repaid when the home is sold. The work is choosing how much to draw and when, finding the lender whose rules fit your age and home, and making sure you and your family know what will be left.
On most loans we arrange, the lender pays us a commission and you pay us no fee. Where a fee would apply, we tell you before you apply, in writing.
For the background on how these loans work and what the regulator found when it reviewed them, read our guide What is a reverse mortgage?.
We show you the equity left at the end before anything else
Before you apply, a lender or broker has to take you through equity projections from ASIC, the government's credit regulator: your figures, a rate two points higher, and no rise in the home's value. We go through all three with you in plain numbers, and we start with the one where the house does not go up.
We size the loan to the purpose, not the limit
The maximum a lender will advance at your age is rarely the right amount. Every dollar you draw early is charged interest for longer, and then interest on that interest, so a smaller lump sum or regular payments over a few years usually leaves far more equity than taking the limit on day one.
We compare the lenders that offer reverse mortgages
Few lenders offer them, and they differ on minimum age, how much they lend at each age, minimum property value and whether they lend outside the metro area. We match your age, your home and what the money is for to the lender whose rules fit.
We check the other options with you first
Downsizing, the government's Home Equity Access Scheme and an ordinary loan all do some of the same job. We put the reverse mortgage next to each one so you can see which leaves you better off, and we say so when it is not the reverse mortgage.
We welcome your family or adviser to the meetings
A reverse mortgage changes what is left for your estate, so it is worth having the people affected in the room. We also recommend independent legal and financial advice before you sign, and we will wait while you get it.
We stay on the loan after settlement
Rates move and plans change. We review the loan with you over time, check what the balance is doing against the projections, and talk through voluntary repayments if you want to slow it down and your lender allows them.
Reverse mortgage calculator
See how much of your home could be left in 5, 10 and 20 yearsPut in your home's value, what you want to draw and when, and the calculator shows the amount owing and the equity left over time. It uses the same method and default assumptions as ASIC's Moneysmart calculator, and runs the rate two points higher and no price growth alongside your figures.
Project the equity left in your home
Lenders set how much you can borrow from the younger borrower's age.
Your best estimate, or a recent appraisal from a local agent.
Leave at $0 for a lump sum only.
Default 7%. Change it to the rate a lender quotes you.
Default 3%. A lower figure is the safer test.
Equity left after 15 years, at age 85
$1,153,336
That is 87% of the home's projected value.
- Projected home value
- $1,324,272
- Amount owing
- $170,937
- Money you received
- $60,000
- Interest and fees added
- $110,937
- General limit at 7030% of the home's value. Each lender sets its own limit.
- $255,000
An estimate, not a prediction or an offer. It uses the same method and default assumptions as the Moneysmart reverse mortgage calculator, last updated by Moneysmart on 27 October 2026: the rate and growth stay constant, no repayments are made, and fees are added to the loan. A broker must show you ASIC's own projections before helping you apply, and a lender before it assesses your application. Lending is subject to approval.
Talk to us about a reverse mortgageEquity left under the three projections a lender must show you
| After | Your figures | Rate 2 points higher | No price growth |
|---|---|---|---|
| 5 yearsage 75 | $900,325 | $891,442 | $764,942 |
| 10 yearsage 80 | $1,021,749 | $995,247 | $729,420 |
| 15 yearsage 85 | $1,153,336 | $1,093,990 | $679,063 |
| 20 yearsage 90 | $1,292,870 | $1,174,645 | $607,676 |
“Rate 2 points higher” keeps your growth figure and adds two percentage points to the rate. “No price growth” keeps your rate and holds the home at today’s value. Method matched to the Moneysmart reverse mortgage calculator on 2 November 2026, where you can also run it against a named lender’s limits.
Each tool has a page of its own explaining every figure it uses: reverse mortgage calculator.
Reverse mortgage lenders
Who offers reverse mortgages, and from what ageEach lender sets its own minimum age and how much it lends at each age, as a share of your home's value. These are the lenders listed in Moneysmart's calculator, with the limits it applies to each, as at 2 November 2026.
 Heartland Reverse Mortgages
Minimum age
55
How much it lends
Lends 15% of the home's value at 55, rising one point a year. Also has aged care and second property products.
 Household Capital
Minimum age
55
How much it lends
Same limit by age as Heartland, up to 55% at 95. Home worth at least $600,000.
 Brighten
Minimum age
55
How much it lends
Same limit by age, up to 55% at 95. Home worth at least $200,000.
 P&N Bank Easy Living Loan
Minimum age
65
How much it lends
A Perth lender. Lends 20% at 65 in the metro area and 10% outside it, up to $300,000.
 Inviva
Minimum age
55
How much it lends
Same limit by age as Heartland, rising past 90. Also has a five year term product for homes worth $750,000 or more.
Limits change and each lender also has its own credit rules. Tell us your age, your home's value and what the money is for, and we will tell you which of these fit.
Who a reverse mortgage suits
The homeowners we arrange reverse mortgages forA reverse mortgage suits somebody who owns their home, wants to stay in it, and needs money for a purpose with an end to it. These are the situations where one usually fits.
Perth homeowners aged 55 or over who own their home outright or owe very little on it
Retirees who want to stay in their home and need money for a specific purpose, such as renovations or a car
Owners paying for changes that let them stay at home longer, such as a step-free shower or a ramp
Couples topping up retirement income with regular payments rather than one large draw
Owners who have weighed up downsizing and would rather stay where they are
Families who want an independent broker in the room when a parent is considering one
How our loan process works
Five steps, from the first conversation to settlementA reverse mortgage goes through the same five steps as every loan we arrange, and we take you through the equity projections before anything goes to a lender.
Start an application
You send us the basics and we work out what you could borrow and which lenders will look favourably at your situation.
Read this step in full: Start an applicationWhat you need
Income, debts, deposit
Get pre-approved
We put your file to the lender that fits and bring back a pre-approval in writing, subject to lender approval and your circumstances.
Read this step in full: Get pre-approvedWhat we do
Match the lender to your file
Get officially approved
Once your offer is accepted, the lender orders its valuation and issues formal approval.
Read this step in full: Get officially approvedWhat we do
Chase the lender, so you do not have to
Prepare for settlement
We go through the loan documents with you before you sign anything, then coordinate the lender and your settlement agent.
Read this step in full: Prepare for settlementWhat you need
Your questions, asked early
Stay up to date
After settlement we keep the loan under review as rates move and your circumstances change.
Read this step in full: Stay up to dateWhat we do
Review it, and tell you first
Step 1 of 5 · Start an application
About our independent mortgage brokers
The brokers who arrange your reverse mortgageIndependent means no franchise above us and no lender owning a share of the business. Nobody upstairs sets us a monthly target, and we would rather you borrow what the job needs and keep more of your home. We have been writing loans in Perth for 21+ years.
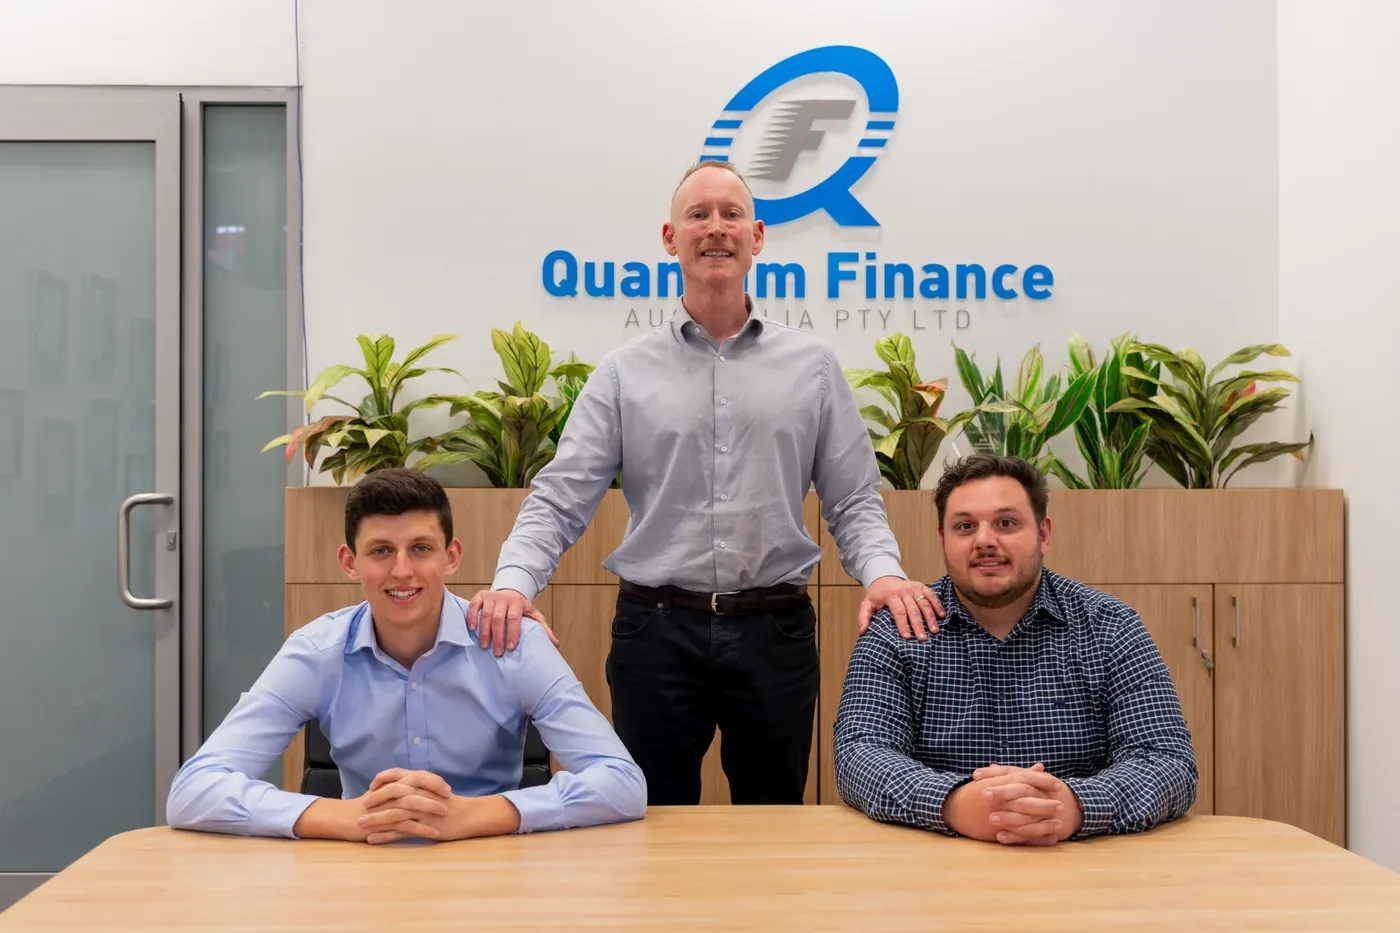
Gavin Harrigan has been broking from West Leederville since 2005. Today it runs on a small team, Gavin Harrigan, Justin Richardson and Xavier Prescott, each with their qualifications on the page. You deal with the person who writes your loan, before settlement and after it.
The work runs from a first home loan, through refinancing and investment lending, out to construction, small developments and commercial property. Same broker, whichever end of that you are at.
- VerifiedBroking since 2005
- VerifiedOver $1 billion in loans settled
- VerifiedAustralian Credit Licence 389083
- VerifiedMoneyQuest accredited
- VerifiedMember of the Finance Brokers Association of Australia (FBAA)
- Verified40+ lenders on the panel
Fifteen minutes is usually enough to tell you where you stand. No cost, no obligation, and any lending is subject to approval and your circumstances.
Why choose us for a reverse mortgage
Why homeowners use us for a reverse mortgageWe are not owned by a lender or a franchise, so the advice on your loan comes from us and nobody above us.
- Included
No franchise, no head office quota
We do not pay a franchise fee, so nobody upstairs sets a monthly target for us to hit. That removes the main reason a broker recommends the wrong loan.
- Included
No lender owns a share of us
The banks have no stake in this business and no claim on where files go. Your bank has one loan to sell you. We do not.
- Included
40+ lenders, one shortlist
We compare 40+ bank and non-bank lenders, then explain why the shortlist looks the way it does. Policy differences decide more applications than rate does.
- Included
We will tell you when the answer is no
If refinancing does not actually save you money, we say so and you leave the loan where it is. A wrong loan costs more than the fee it earns.
- Included
The same broker after settlement
You keep dealing with the person who wrote the loan. We review it as rates and your circumstances change, not once and then never again.
What our clients say
In their words, not oursReviews left by people we have settled loans for, pulled straight from the platform they were written on.
Our lender panel
We compare 40+ lenders, and know which offer reverse mortgagesMajor banks, second-tier banks and specialist lenders, reached through MoneyQuest, the aggregator that gives brokers access to lenders. Only a handful of them offer reverse mortgages, and the lender table on this page shows which.
A selection of the lenders we are accredited with. Ask us who else is on the panel for your situation.
Our lending guides
Read this before you borrow against your homeOur guide to how a reverse mortgage works, the protection the law gives you and the questions to ask first, plus our general guides to borrowing. Each one is written by one of our brokers, under their own name.
Loan types
What is a reverse mortgage?
How they work, the protection the law gives you, and what the regulator found when it looked at 17,000 of them.
Read it: What is a reverse mortgage?
Approvals
Credit scores and home loans
What is on your file, how long it stays there, and what a lender does with it.
Read it: Credit scores and home loans
Borrowing power
How much can I borrow?
Income less commitments, tested at a rate higher than the one you would pay.
Read it: How much can I borrow?
First home buyers
The First Home Owner Grant in WA
Who qualifies, what it is worth, and every figure dated to its WA Government source.
Read it: The First Home Owner Grant in WA
Meet our Perth mortgage brokers
You get a broker, not a call centreThere are three of us, and you can ring any of us directly. The person who runs your projections is the person you ring when you have a question in five years.
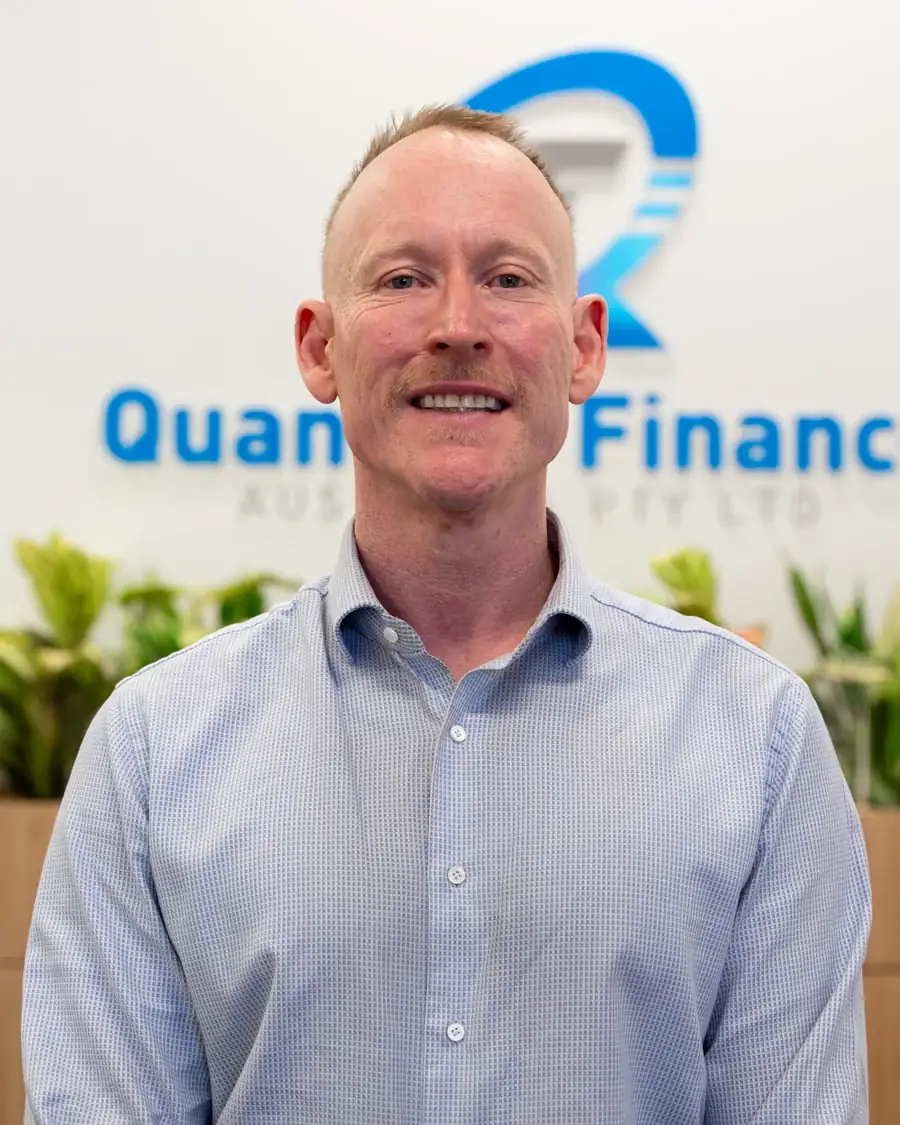
Gavin Harrigan
Managing Director
Broking since 2005, four-time Top 100 broker and a PLAN Australia Hall of Fame member.
- Bachelor of Commerce, Applied Finance and Commercial Law, Curtin University
- Diploma of Finance and Mortgage Broking Management, AAMC Training Group
- PLAN Australia Hall of Fame member
- Elite Broker status
- Top 100 Brokers, four times
Justin Richardson
Loan Consultant
Business and law background, and a habit of making the process feel simple.
- Bachelor of Commerce, Business Law and Marketing, Curtin University
- Bachelor of Laws (in progress), Murdoch University
Xavier Prescott
Loan Consultant
Fresh qualifications, a competitor's discipline, and a lot of patience.
- Diploma of Finance and Mortgage Broking Management
Common questions about reverse mortgages in Perth
How much can I borrow with a reverse mortgage at my age?
Most lenders start at 15% of your home's value at 55 and add about one percentage point a year, so roughly 20% at 60, 25% at 65 and 30% at 70. That is the general limit in Moneysmart's calculator. Some lenders lend less, and each lender also sets a minimum age and property value.
What is the minimum age for a reverse mortgage?
It depends on the lender. Moneysmart's calculator lists Heartland, Household Capital, Brighten and Inviva from age 55, and P&N Bank from 65. For a couple, the limit is set by the younger borrower's age, which usually means a smaller loan than the older partner could get alone.
Can I lose my home with a reverse mortgage?
You can stay in your home until you sell, move out permanently or die, as long as you keep to the loan terms, such as insuring and maintaining the property. Loans taken out since 18 September 2012 also carry negative equity protection, so you cannot owe more than the home is worth.
Will a reverse mortgage affect my Age Pension?
It can. Money you draw and hold in the bank, or spend on assets, may count under Centrelink's income and assets tests. Ask Services Australia's Financial Information Service, which is free, to look at your situation before you decide how much to draw and when.
What is the Home Equity Access Scheme?
It is the government's own version of a reverse mortgage, run by Services Australia for people of Age Pension age. The rate was 3.95% a year, compounding fortnightly, as at 2 November 2026, and payments are made fortnightly with a limited lump sum option. We compare it with a private loan for you.
What will a lender show me before I take one out?
Equity projections from ASIC's reverse mortgage calculator, covering your figures, interest rates two points higher, and no growth in your home's value. A broker must show you them before helping you apply, and a lender before it assesses your application. Ask for a printed copy and take it home before you decide anything.
Does Quantum Finance arrange reverse mortgages in Perth?
Yes. We arrange reverse mortgages for Perth homeowners, compare the lenders that offer them, and go through the equity projections with you and your family. We also check downsizing and the Home Equity Access Scheme with you, and say so if either suits you better.
Related loans we arrange
Other ways to use the equity in your homeSome homeowners are better served by one of these. If you are not sure which, it is the same broker and the same conversation.
Line of Credit Home Loans
Equity turned into an approved limit you draw on, with the limit set to a purpose.
Learn moreabout Line of Credit Home Loans
Cash Out Refinancing
Release equity from a property you already own, with the purpose evidenced and the split structured properly.
Learn moreabout Cash Out Refinancing
Debt Consolidation
Roll card, car and personal debt into the mortgage, with the cost over the whole term shown first.
Learn moreabout Debt Consolidation
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Any figures shown are estimates only. Lending is subject to approval, and to the lender's terms, conditions, fees and charges. Consider whether the information is appropriate for you before acting on it.
Get in touch
Talk to us about a reverse mortgageSend us your details and a broker rings you back on the number you give us. We run the projections on the call, once we know your age, your home's value and what the money is for. You are welcome to have family on the call.
Would rather just talk?
Ringing is quicker than waiting for us to ring you, and you get a broker rather than a queue.
1300 813 113