Home loans by occupation
Quantum Finance arranges home loans by occupation in Perth. We take the time to learn how your work and pay run, then check which of 40+ lenders have a policy for your occupation, and whether one would waive lenders mortgage insurance. That is the insurance you normally pay to protect the lender when you have saved less than twenty per cent.
- We find out whether any lender has a policy for your occupation.
- We check whether any lender would waive the insurance for your occupation, without you having to ask.
- We compare 40+ lenders, because each one keeps a different list of occupations.
- Subject to lender approval and your circumstances.
- Years broking
- 21+Years broking
- Loans settled
- $1B+Loans settled
- Credit licence
- ACL 389083Credit licence
- Lenders compared
- 40+Lenders compared
Find your occupation
Home loans for your line of workPick your occupation to see how lenders treat that work and pay. More pages are on the way, so search for yours, or tell us what you do if it is not listed.
- Home loans for doctorsRead the page
- Home loans for nursesRead the page
- Home loans for lawyersRead the page
- Home loans for teachersRead the page
- Home loans for dentistsRead the page
- Home loans for accountantsPage coming soon
- Home loans for veterinariansPage coming soon
- Tradie home loansPage coming soon
- Home loans for pharmacistsPage coming soon
- Home loans for police officersPage coming soon
- Home loans for medical specialistsPage coming soon
- Home loans for medical graduatesPage coming soon
- Home loans for midwivesPage coming soon
- Home loans for paramedicsPage coming soon
- Home loans for physiotherapistsPage coming soon
- Home loans for psychologistsPage coming soon
- Home loans for optometristsPage coming soon
- Home loans for radiographersPage coming soon
- Home loans for occupational therapistsPage coming soon
- Home loans for chiropractorsPage coming soon
- Home loans for podiatristsPage coming soon
- Home loans for speech pathologistsPage coming soon
- Home loans for firefightersPage coming soon
- Home loans for defence force membersPage coming soon
- Home loans for engineersPage coming soon
- Home loans for architectsPage coming soon
- Home loans for actuariesPage coming soon
- Home loans for financial plannersPage coming soon
- Home loans for mining workersPage coming soon
- Home loans for pilotsPage coming soon
- Home loans for IT professionalsPage coming soon
- Home loans for public servantsPage coming soon
- Home loans for academicsPage coming soon
- Home loans for real estate agentsPage coming soon
- Home loans for self-employed borrowersPage coming soon
- Home loans for contractorsPage coming soon
- Home loans for truck driversPage coming soon
- Home loans for chefsPage coming soon
- Home loans for hairdressersPage coming soon
- Home loans for farmersPage coming soon
- Home loans for support workersPage coming soon
- Home loans for childcare workersPage coming soon
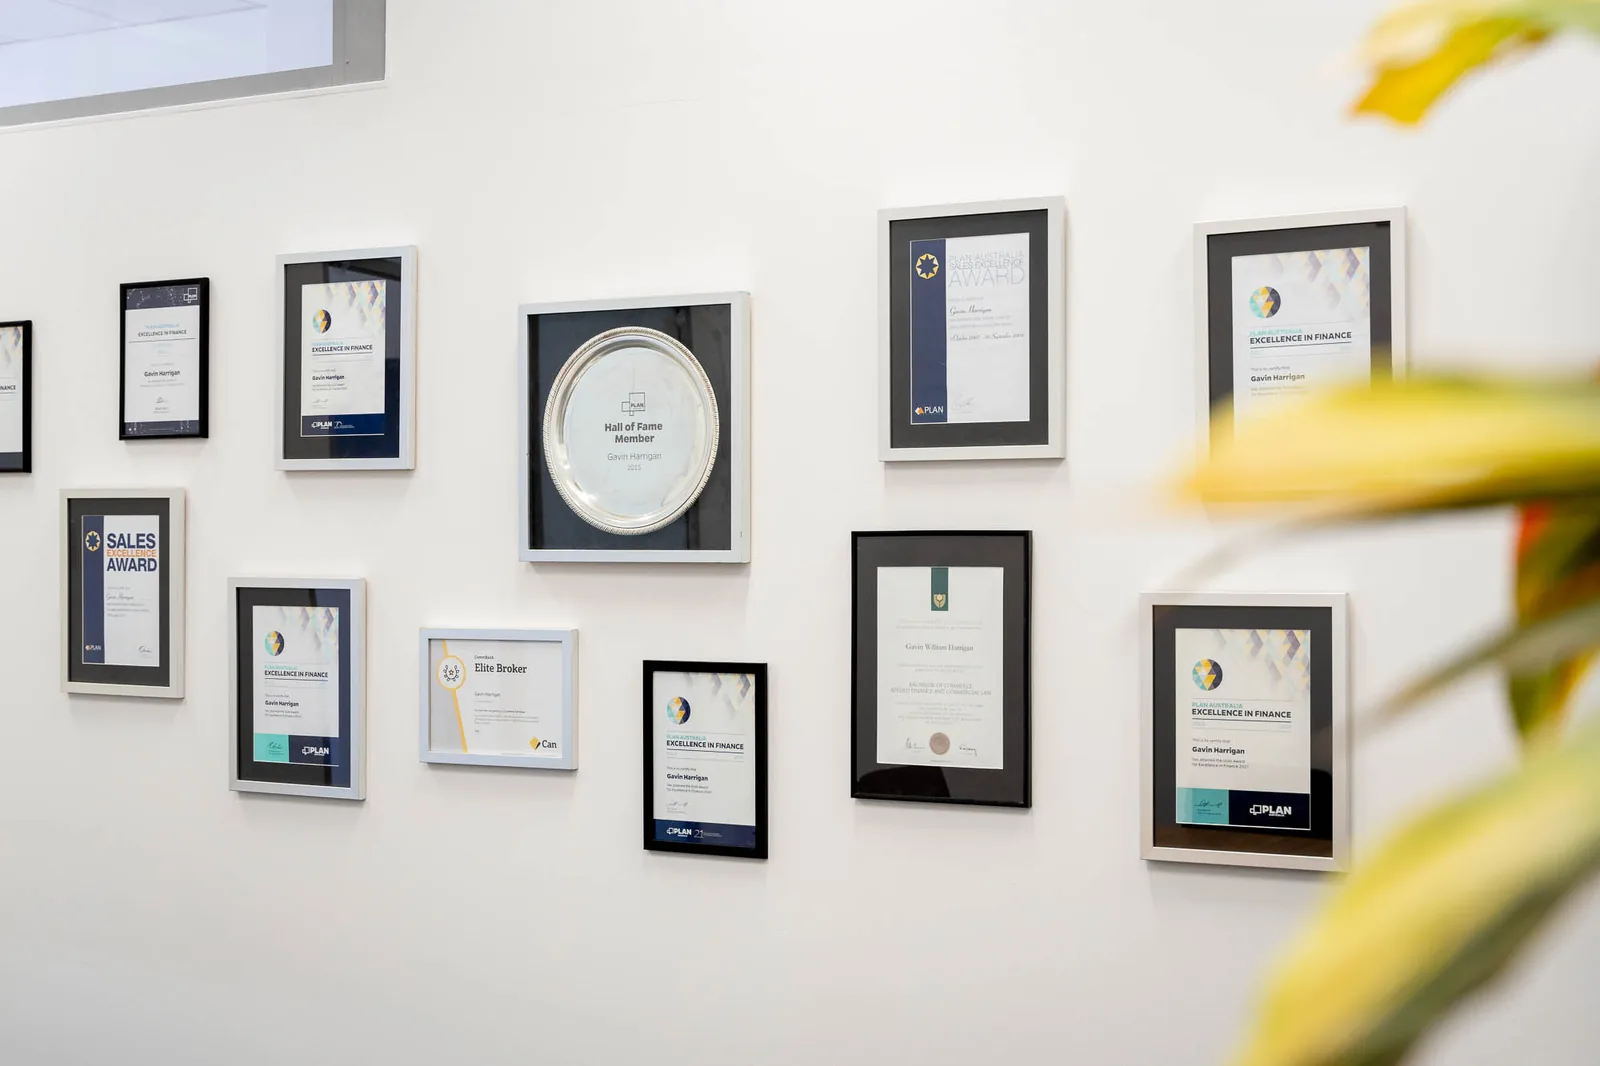
Our awards and recognition
Awarded by the people who see every broker’s numbers
Diamond Club
2026
Money Quest Group
Diamond Club
2025
Money Quest Group
Diamond Club
2024
Money Quest Group
Mortgage Broker of the Year
2023/24, National, highest dollar volume settled
Southern Cross Broker Network
Excellence in Finance, Gold
2021
PLAN Australia
Excellence in Finance, Gold
2020
PLAN Australia
Hall of Fame
Valued partner, 15 years
PLAN Australia
Elite Broker
2021
Broker Value Proposition
Premium Broker
ANZ
Individual Excellence Award
2016
Specialist Finance Group
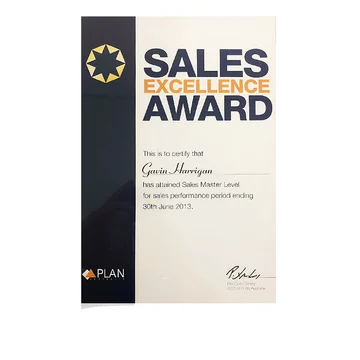
Sales Excellence Award
PLAN Australia
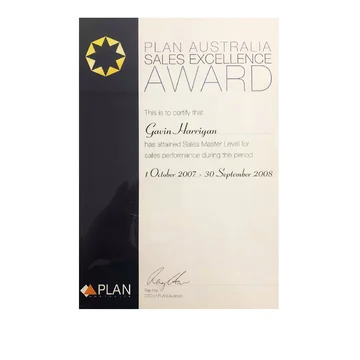
Sales Master Award
PLAN Australia
Top 100 Brokers
Four times
Australian Broker
What our professionals service does
The work we do when your occupation could change the loanA home loan for professionals is a standard home loan written under a lender's policy for particular occupations. The work is finding the lenders whose policy recognises yours, then comparing the whole loan, not just the waiver.
Most residential loans are paid for by the lender through commission rather than by you. Where a fee would apply, we tell you before you apply, in writing.
Sometimes no lender's list includes your occupation. We say so early, then compare our whole panel, the 40+ lenders we can apply to, on their normal terms.
We check whether an insurance waiver applies to you
Several lenders waive lenders mortgage insurance for particular occupations, and each one keeps its own list. We check yours against the panel before you assume the premium is unavoidable, and we tell you when no lender's list includes it.
We compare 40+ lenders on occupation policy
Lenders differ on which occupations qualify, on the rate, and on how much of the property's value they will lend, called the loan-to-value ratio. A single bank cannot show you those differences, because it only knows its own policy.
We cost the premium a waiver would remove
The premium varies by lender, by loan size and by how far under twenty per cent you are. It is usually added to the loan. Once you know that figure, you know what a waiver is worth to you.
We read your income the way a lender will
Allowances, overtime, bonuses and contract income are counted differently from one lender to the next, and some lenders count only part of them. We work out what each lender will accept on your payslips before anything is submitted.
We weigh the waiver against the whole loan
A loan with a waiver can carry a higher rate or fees, and over the years those can cost more than the premium. We compare the whole loan, so the insurance saving is one line in the comparison rather than the only one.
We submit once, to a lender whose policy fits
Multiple declines in a short window damage a credit file. We check your occupation, income and deposit against each lender's rules first, so your application goes to one lender instead of several.
Work out what a waiver is worth
The premium a waiver would remove, and what you can borrowEstimate the insurance premium a waiver could save you, and how much a lender might lend on your income. Both figures move with the lender, so treat them as a starting point for the conversation.
Work out which LVR band you are in
The lender uses its own valuation, which is not always the price you agreed.
What is going towards the property itself, after transfer duty and costs are paid.
80% is where lenders mortgage insurance normally stops applying. Move this to whatever band your lender has told you about.
Your loan-to-value ratio
91.0%
Above 80%, so lenders mortgage insurance would normally apply.
- The loan you would need
- $546,000
- Your deposit as a percentage
- 9.0%
- Deposit for a 80% ratioWhich would leave a loan of $480,000.
- $120,000
- Extra deposit needed to get thereCrossing a band can be worth far more than the dollars suggest.
- $66,000
This tool does not price the premium, and that is deliberate. LMI premiums are set by the mortgage insurers and vary by insurer, lender, LVR band and loan size, so there is no universal table anybody can honestly publish. What you see above is the part that is the same everywhere: where you sit against 80% and what it takes to move. For an actual figure, we run your numbers at the lenders whose insurer pricing suits your ratio and come back with a quoted premium. This is an estimate, not an approval.
Get a real LMI figureWork out what you could borrow
What actually lands in your accounts, so $9,000 a month. Include a partner if you are buying together.
Groceries, fuel, insurance, childcare, subscriptions. Lenders apply a minimum benchmark, so a low figure here will not be taken at face value.
Car, personal, HECS, existing mortgages.
The limit, not the balance.
Lenders count between 2.5% and 3.8% of every card limit as a repayment, whether you owe anything or not.
An example figure to change, not a rate on offer.
Lenders test you at a rate above the one you pay. Three percentage points is the level APRA expects, so you are being assessed at 9.00%.
Used only for the price guide below.
You could borrow around
$684,000
Based on $5,500 a month left over, assessed at 9.00%.
- Monthly income counted$108,000 a year, after tax, divided by twelve.
- $9,000
- Monthly surplus a lender would seeIncome less expenses, commitments and card limits.
- $5,500
- Card limits counted as a repayment3.8% of $0 a month.
- $0
- Assessment rate used6.00% plus a 3.00% buffer.
- 9.00%
- Repayment at the loan rateWhat you would actually pay each month, not the tested figure.
- $4,098
- Rough price guide with your depositStamp duty and fees come out of the deposit, so the real figure is lower.
- $804,000
This is an estimate, not a pre-approval. Every lender counts income, expenses and commitments differently, and the spread between the most and least generous on the panel is often more than $150,000 on the same file. Lending is subject to approval.
Get a real numberEach tool has a page of its own explaining every figure it uses: lmi calculator and borrowing power calculator.
How lenders treat professionals
Four ways professionals borrow, and what each one meansBorrowers often hear that professionals get special home loans. In practice it comes down to a few lender policies, and none of them applies to every lender or every occupation.
- Lenders mortgage insurance waiver
Tends to suit
Eligible occupations borrowing with less than twenty per cent saved
Worth knowing
The occupation list, the maximum ratio and the rate differ by lender
- Allowances, overtime and bonus income
Tends to suit
Professionals paid partly outside their base salary
Worth knowing
Lenders count these differently, and some count only part of them
- Family guarantee
Tends to suit
Buyers whose occupation does not attract a waiver
Worth knowing
A family member puts up part of the value of their home as extra security. That removes the premium in most cases, and they take on a real obligation.
- Standard lending policy
Tends to suit
Borrowers whose occupation is not on any lender's list
Worth knowing
Every lender we work with is still compared, and the insurance is charged the usual way
You do not need to know which lender lists your occupation. Tell us what you do and how you are paid, and we check the panel for you.
Who home loans for professionals suit
The borrowers we check occupation policy forOccupation policy matters most when the deposit is under twenty per cent or the income is not a simple salary. These are the situations that arrive most often.
Medical professionals buying with less than twenty per cent saved
Professionals told by one bank that the insurance premium cannot be avoided
Borrowers whose pay includes allowances, overtime or bonuses that lenders read differently
Professionals early in their career, whose income is rising faster than their savings
Anyone unsure whether their occupation appears on any lender's list
How the process works for professionals
Five steps, with your occupation checked before step twoThe process is the same five steps as any loan we write, with your occupation and income checked against lender policy before anything is submitted. Here is the whole thing, start to finish.
Start an application
You send us the basics and we work out what you could borrow and which lenders will look favourably at your situation.
Read this step in full: Start an applicationWhat you need
Income, debts, deposit
Get pre-approved
We put your file to the lender that fits and bring back a pre-approval in writing, subject to lender approval and your circumstances.
Read this step in full: Get pre-approvedWhat we do
Match the lender to your file
Get officially approved
Once your offer is accepted, the lender orders its valuation and issues formal approval.
Read this step in full: Get officially approvedWhat we do
Chase the lender, so you do not have to
Prepare for settlement
We go through the loan documents with you before you sign anything, then coordinate the lender and your settlement agent.
Read this step in full: Prepare for settlementWhat you need
Your questions, asked early
Stay up to date
After settlement we keep the loan under review as rates move and your circumstances change.
Read this step in full: Stay up to dateWhat we do
Review it, and tell you first
Step 1 of 5 · Start an application
About our independent mortgage brokers
The brokers who check your occupation against the panelIndependent means no franchise above us and no lender owning a share of the business. Nobody upstairs sets a monthly target, so we can tell you when no waiver applies. Your bank has one occupation policy; we compare 40+ lenders.
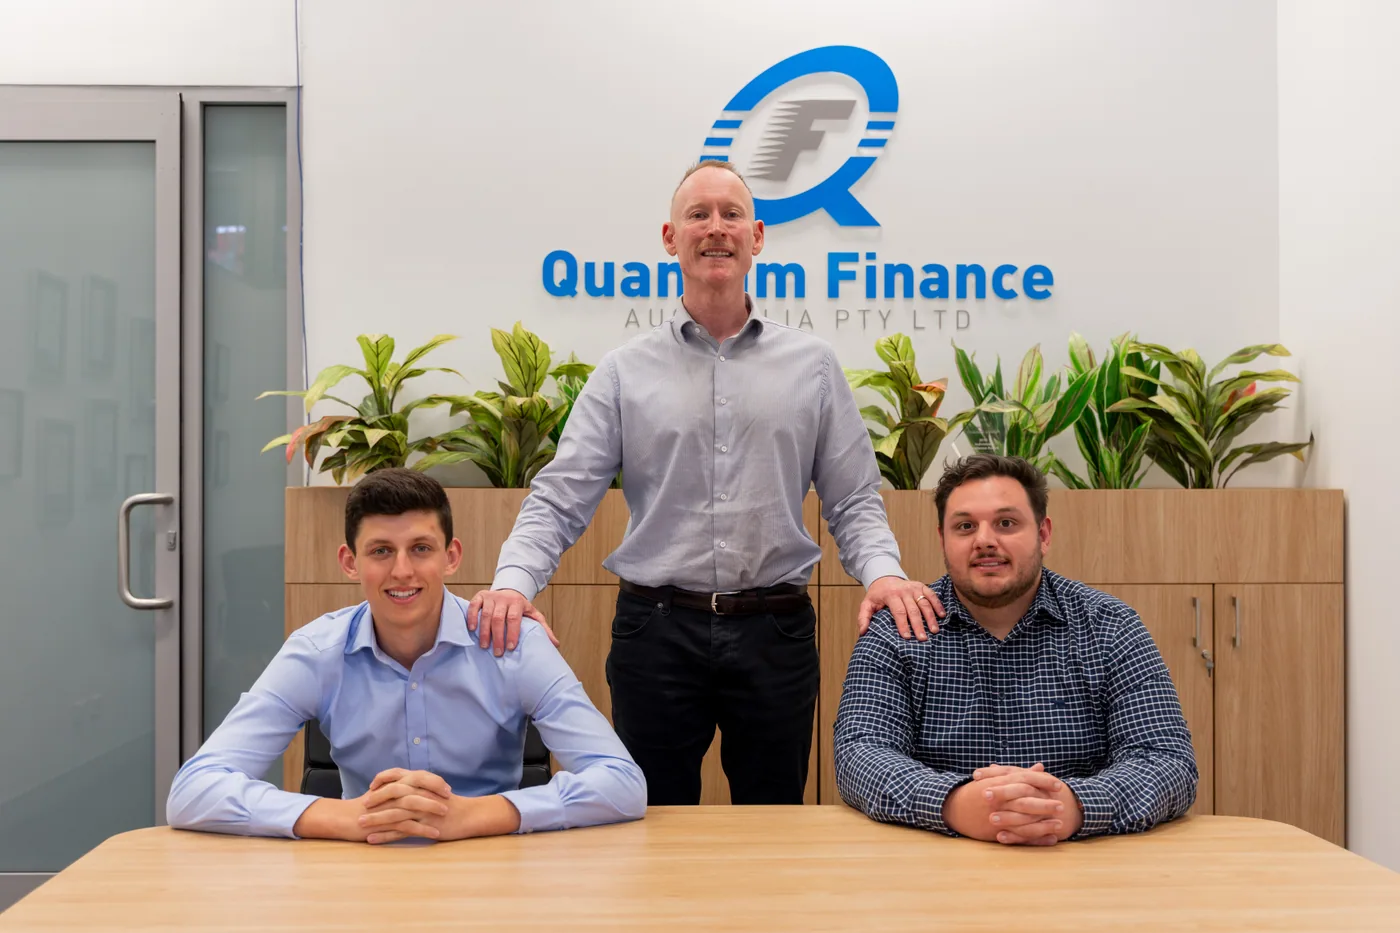
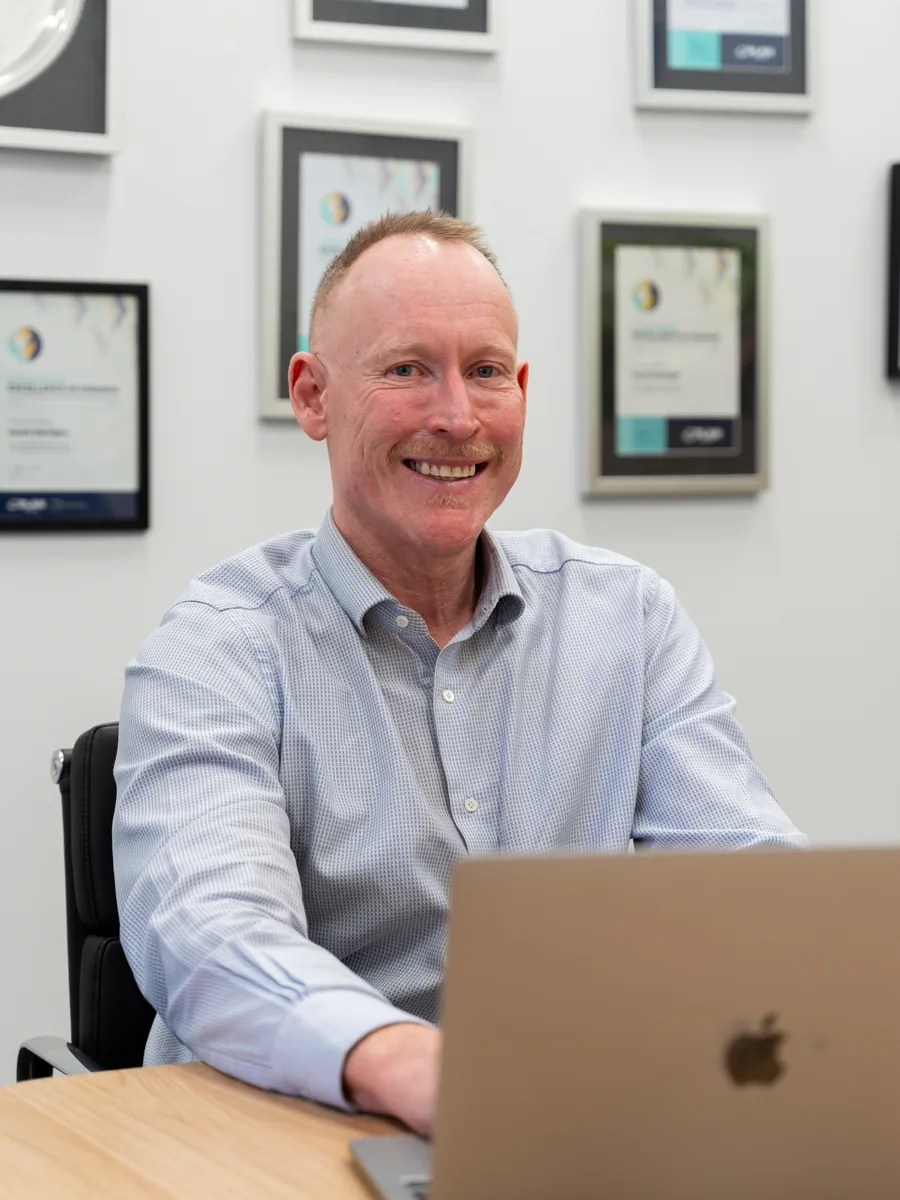
Gavin Harrigan has been broking from West Leederville since 2005. Today it runs on a small team, Gavin Harrigan, Justin Richardson and Xavier Prescott, each with their qualifications on the page. You deal with the person who writes your loan, before settlement and after it.
The work runs from a first home loan, through refinancing and investment lending, out to construction, small developments and commercial property. Same broker, whichever end of that you are at.
- VerifiedBroking since 2005
- VerifiedOver $1 billion in loans settled
- VerifiedAustralian Credit Licence 389083
- VerifiedMoneyQuest accredited
- VerifiedMember of the Finance Brokers Association of Australia (FBAA)
- Verified40+ lenders on the panel
Fifteen minutes is usually enough to tell you where you stand. No cost, no obligation, and any lending is subject to approval and your circumstances.
Why choose us as a professional borrower
Each lender keeps its own list, so somebody should check them allEvery point below is a consequence of how this business is owned, not a slogan about service.
- Included
No franchise, no head office quota
We do not pay a franchise fee, so nobody upstairs sets a monthly target for us to hit. That removes the main reason a broker recommends the wrong loan.
- Included
No lender owns a share of us
The banks have no stake in this business and no claim on where files go. Your bank has one loan to sell you. We do not.
- Included
40+ lenders, one shortlist
We compare 40+ bank and non-bank lenders, then explain why the shortlist looks the way it does. Policy differences decide more applications than rate does.
- Included
We will tell you when the answer is no
If refinancing does not actually save you money, we say so and you leave the loan where it is. A wrong loan costs more than the fee it earns.
- Included
The same broker after settlement
You keep dealing with the person who wrote the loan. We review it as rates and your circumstances change, not once and then never again.
What our clients say
In their words, not oursReviews left by people we have settled home loans for, pulled straight from the platform they were written on.
Our lender panel for professionals
Occupation policy is set lender by lender. We compare 40+Major banks, second-tier banks and non-bank lenders, each with its own view of your occupation. MoneyQuest gives us access to the panel, and 21+ years of writing home loans tells us where to look first.
A selection of the lenders we are accredited with. Ask us who else is on the panel for your situation.
Our home loan guides
Read one before you talk to a lenderPlain-English answers on borrowing capacity, the WA grant with every figure dated to its source, and what pre-approval is worth. Each one carries a broker's name.
Approvals
Credit scores and home loans
What is on your file, how long it stays there, and what a lender does with it.
Read it: Credit scores and home loans
Borrowing power
How much can I borrow?
Income less commitments, tested at a rate higher than the one you would pay.
Read it: How much can I borrow?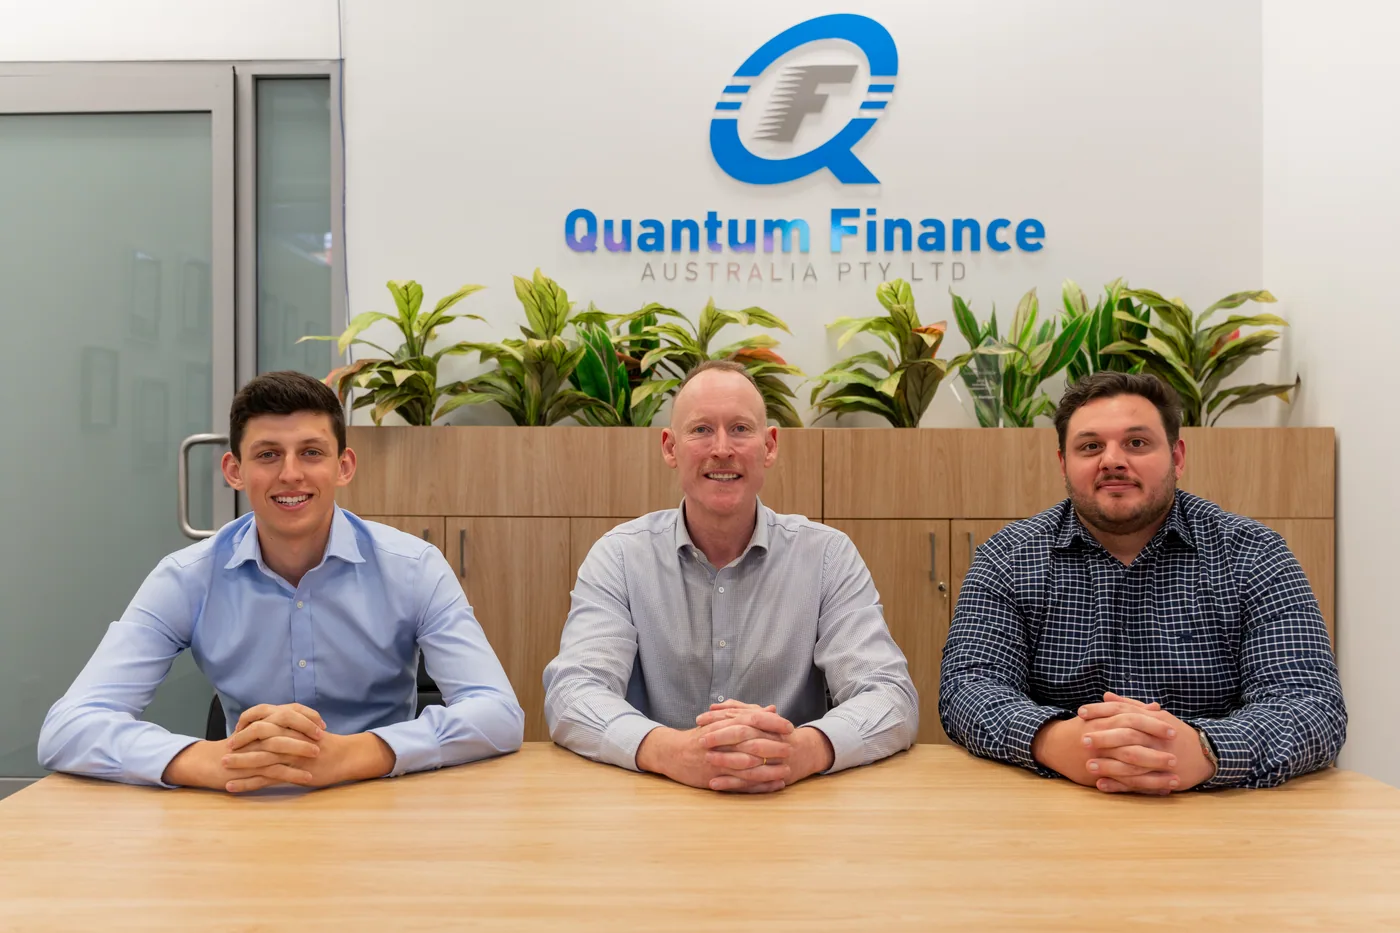
First home buyers
The First Home Owner Grant in WA
Who qualifies, what it is worth, and every figure dated to its WA Government source.
Read it: The First Home Owner Grant in WA
Approvals
Home loan pre-approval, explained
What a lender is actually committing to, and what can still undo it.
Read it: Home loan pre-approval, explained
Meet our Perth mortgage brokers
You get a broker, not a call centreThree people, all named, all reachable. The person who checks your occupation is the person who submits the application and the person who reviews it later.
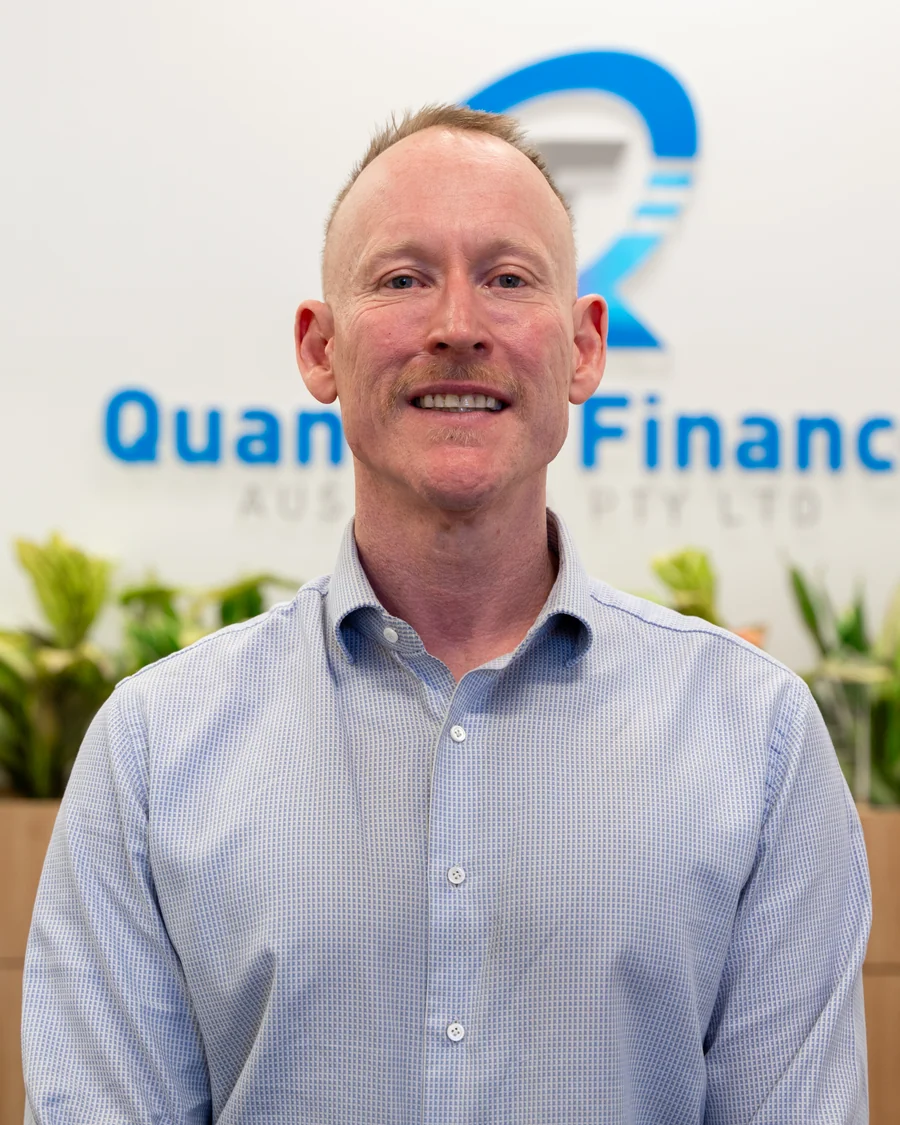
Gavin Harrigan
Managing Director
Broking since 2005, four-time Top 100 broker and a PLAN Australia Hall of Fame member.
- Bachelor of Commerce, Applied Finance and Commercial Law, Curtin University
- Diploma of Finance and Mortgage Broking Management, AAMC Training Group
- PLAN Australia Hall of Fame member
- Elite Broker status
- Top 100 Brokers, four times
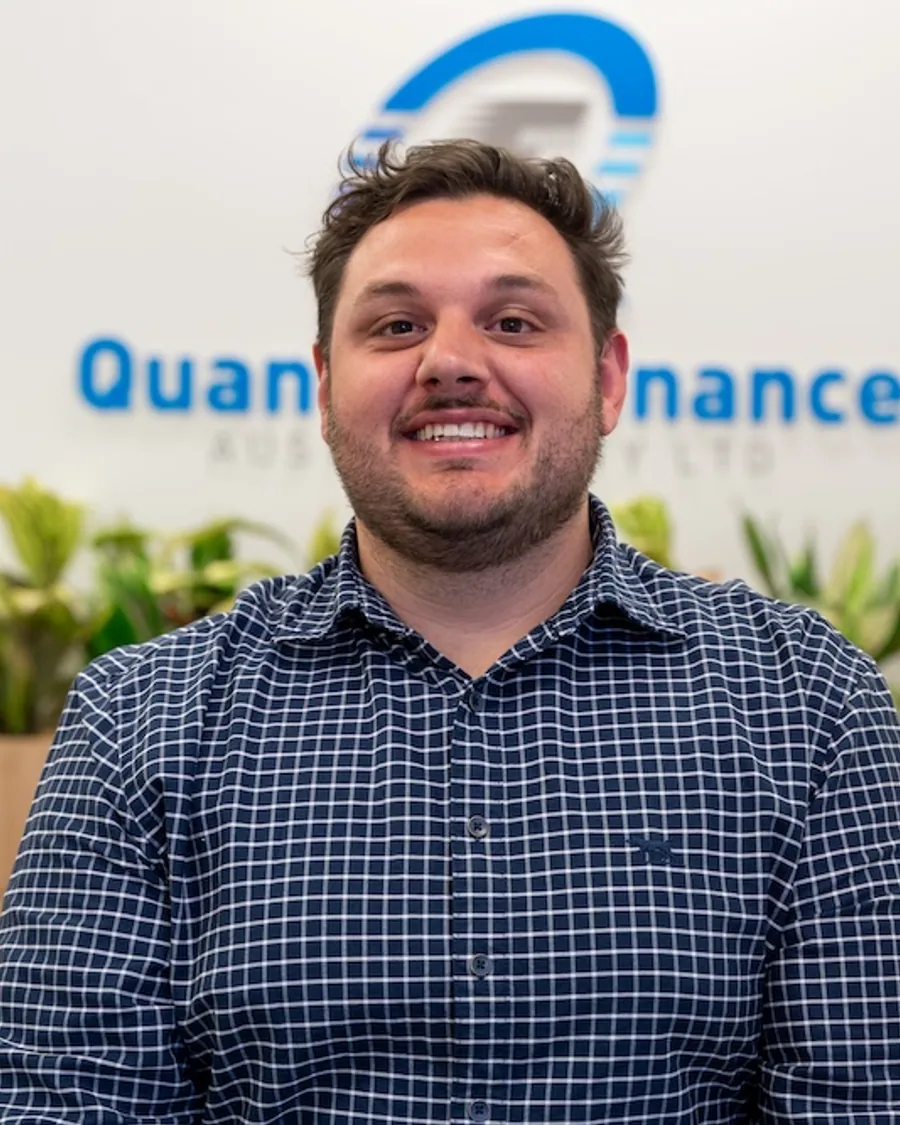
Justin Richardson
Loan Consultant
Business and law background, and a habit of making the process feel simple.
- Bachelor of Commerce, Business Law and Marketing, Curtin University
- Bachelor of Laws (in progress), Murdoch University
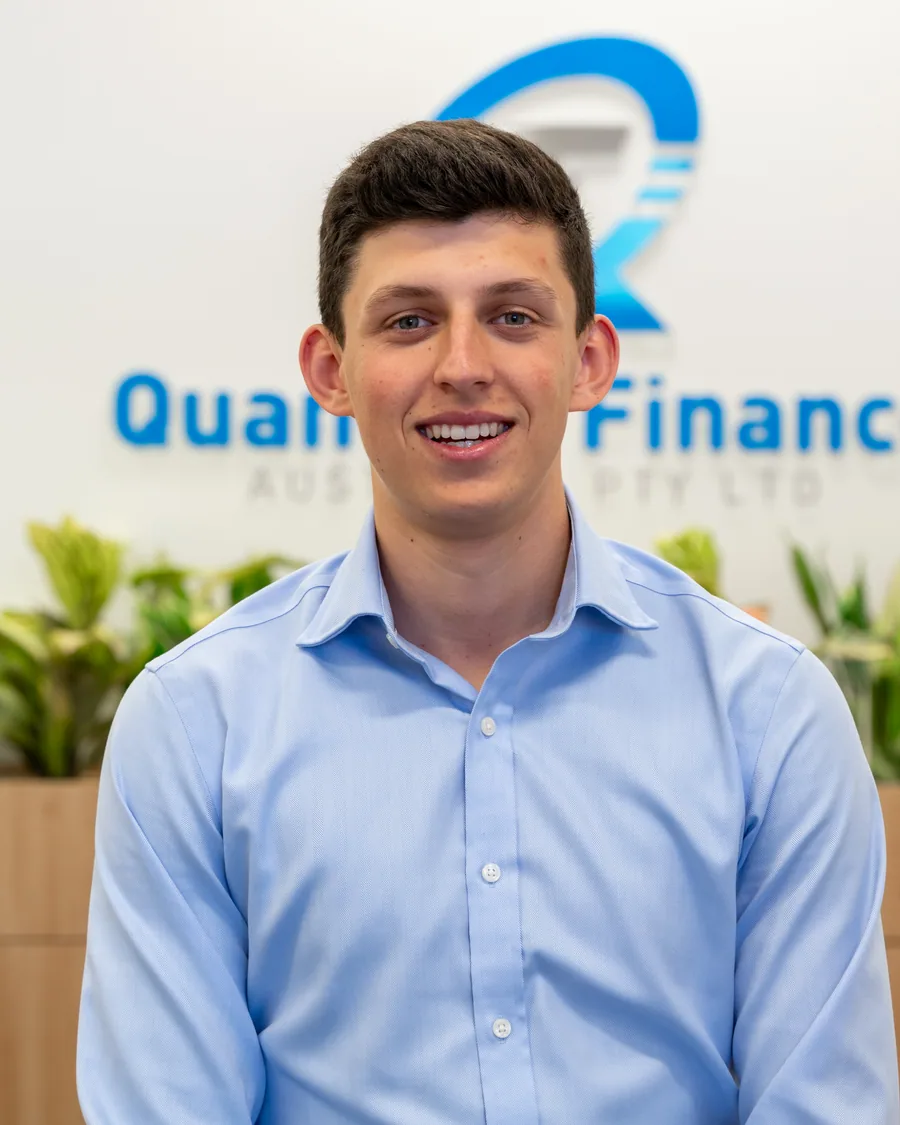
Xavier Prescott
Loan Consultant
Fresh qualifications, a competitor's discipline, and a lot of patience.
- Diploma of Finance and Mortgage Broking Management
Common questions about home loans for professionals
What is a home loan for professionals?
It is a standard home loan written under a lender's policy for particular occupations. The most common feature is a waiver of lenders mortgage insurance for an eligible borrower who has saved less than twenty per cent. The eligible occupations and the terms are set by each lender.
Which occupations can have lenders mortgage insurance waived?
It depends on the lender. Many lenders waive it for eligible medical professionals, and each one keeps its own list, maximum loan-to-value ratio and rate. We check your occupation against the panel rather than guess from a published list.
How much could a waiver save me?
It removes the insurance premium, which could save a substantial one-off cost. The premium varies by lender, by loan size and by how far under twenty per cent you are, so no single figure fits everyone. We work out yours before you commit.
Do I still need a deposit?
Usually some, and stamp duty (called transfer duty in WA), conveyancing and other buying costs come out of the same savings. Each lender sets how much of the property's value it will lend under its occupation policy. Any loan is subject to lender approval and your circumstances.
Will I get a lower interest rate as a professional?
Not automatically. The rate offered under an occupation policy varies by lender, and a waiver is worth comparing against the whole loan, rate and fees included. We compare rates across the panel for your situation before we quote you one.
Do you arrange home loans for my occupation?
Yes. We arrange home loans for borrowers in every occupation. If a lender has a policy for your occupation, we include it in the comparison. If none does, we compare all our lenders on their normal terms.
Related home loans we arrange
What professional borrowers usually read alongside thisMost files touch more than one of these. If yours does, it is the same broker and the same conversation.
Low Deposit Home Loans
Buying with less than twenty per cent saved, with every route costed first.
Learn moreabout Low Deposit Home Loans
Guarantor Home Loans
Family equity used as security instead of a cash deposit, with the obligation explained.
Learn moreabout Guarantor Home Loans
First Home Buyer Loans
Your first place in Perth, from what you can borrow through to the keys.
Learn moreabout First Home Buyer Loans
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Any figures shown are estimates only. Lending is subject to approval, and to the lender's terms, conditions, fees and charges. Consider whether the information is appropriate for you before acting on it.
Get in touch
Talk to us about your occupation and your loanFive questions and you are done. A broker reads it, checks your occupation against the panel, and rings you back on the number you give us.
Would rather just talk?
Ringing is quicker than waiting for us to ring you, and you get a broker rather than a queue.
1300 813 113