Home loans for pharmacists
We arrange home loans for pharmacists in Perth, starting with how you are paid, from a salaried role to locum shifts. Then we check whether any of 40+ lenders would waive lenders mortgage insurance for you. That is the insurance you normally pay when you have saved less than twenty per cent.
- We check whether any lender would waive the insurance for you as a pharmacist.
- We find the lenders that count your locum shifts and second jobs.
- We compare 40+ lenders, because each one sets its own rules for pharmacists.
- Subject to lender approval and your circumstances.
 21+Years broking

 $1B+Loans settled
 40+Lenders compared
Our awards and recognition
Awarded by the people who see every broker’s numbers
Diamond Club
2026
Money Quest Group
Diamond Club
2025
Money Quest Group
Diamond Club
2024
Money Quest Group
Mortgage Broker of the Year
2023/24, National, highest dollar volume settled
Southern Cross Broker Network
Excellence in Finance, Gold
2021
PLAN Australia
Excellence in Finance, Gold
2020
PLAN Australia
Hall of Fame
Valued partner, 15 years
PLAN Australia
Elite Broker
2021
Broker Value Proposition
Premium Broker
ANZ
Individual Excellence Award
2016
Specialist Finance Group
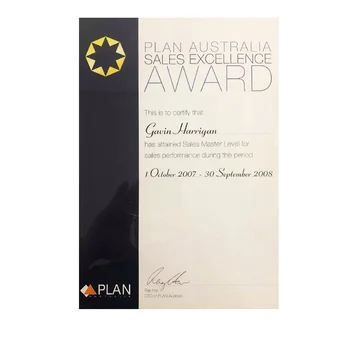
Sales Excellence Award
PLAN Australia
Sales Master Award
PLAN Australia
Top 100 Brokers
Four times
Australian Broker
What we do for pharmacists
The work we do when you are a pharmacist buying a homeA home loan for pharmacists is a standard home loan written under a lender's policy for health professionals. The work is counting every part of your pay a lender will accept, then finding the policy that fits.
On most home loans the lender pays us a commission, so you usually pay us nothing. Where a fee would apply, we tell you before you apply, in writing.
Sometimes no lender will waive the insurance for your situation. We say so early, then compare our whole panel, the 40+ lenders we can apply to, on their normal terms.
We check whether a lender would waive the insurance
Some lenders waive lenders mortgage insurance for registered pharmacists, commonly up to 90 per cent of the property's value and at some lenders 95. Some also set a minimum income from your pharmacy work. We check your situation against the panel and tell you early if none fits.
We count every pharmacy job a lender will accept
If you work in more than one pharmacy, or add locum shifts to a main role, lenders differ on what they count. Some count income from every job and others leave a second job out. We find the lenders that will count the most of yours.
We check your registration first
Lenders want current registration as a pharmacist with AHPRA, the national agency that registers health practitioners. If you are newly registered, lenders differ on how they treat you. We check your status against each lender's policy before you apply.
We sort out the paperwork for locum and owner income
Locum work billed through an ABN, an Australian Business Number, is usually assessed like self-employed income. Pharmacy owners are usually assessed on one to two years of tax returns, depending on the lender. We collect the documents once, for the lender that suits you.
We weigh the waiver against the whole loan
Some lenders take pharmacists to 95 per cent of the property's value without the insurance. A loan at that level can carry a higher rate or fees, and over the years those can cost more than the premium. We compare the whole loan, rate and fees included.
We submit once, to a lender whose policy fits
Every application you lodge is recorded as an enquiry on your credit file, and the next lender can see it. We check your registration, income and deposit against each lender's rules first. Then your application goes to one lender instead of several.
Work out what a waiver is worth
The premium a waiver would remove, and what you can borrowEstimate the insurance premium a waiver could save you, and how much a lender might lend on your income. Both figures move with how much of your locum or second-job income a lender counts, so treat them as a starting point.
Work out which LVR band you are in
The lender uses its own valuation, which is not always the price you agreed.
What is going towards the property itself, after transfer duty and costs are paid.
80% is where lenders mortgage insurance normally stops applying. Move this to whatever band your lender has told you about.
Your loan-to-value ratio
91.0%
Above 80%, so lenders mortgage insurance would normally apply.
- The loan you would need
- $546,000
- Your deposit as a percentage
- 9.0%
- Deposit for a 80% ratioWhich would leave a loan of $480,000.
- $120,000
- Extra deposit needed to get thereCrossing a band can be worth far more than the dollars suggest.
- $66,000
This tool does not price the premium, and that is deliberate. LMI premiums are set by the mortgage insurers and vary by insurer, lender, LVR band and loan size, so there is no universal table anybody can honestly publish. What you see above is the part that is the same everywhere: where you sit against 80% and what it takes to move. For an actual figure, we run your numbers at the lenders whose insurer pricing suits your ratio and come back with a quoted premium. This is an estimate, not an approval.
Get a real LMI figureWork out what you could borrow
What actually lands in your accounts, so $9,000 a month. Include a partner if you are buying together.
Groceries, fuel, insurance, childcare, subscriptions. Lenders apply a minimum benchmark, so a low figure here will not be taken at face value.
Car, personal, HECS, existing mortgages.
The limit, not the balance.
Lenders count between 2.5% and 3.8% of every card limit as a repayment, whether you owe anything or not.
An example figure to change, not a rate on offer.
Lenders test you at a rate above the one you pay. Three percentage points is the level APRA expects, so you are being assessed at 9.00%.
Used only for the price guide below.
You could borrow around
$684,000
Based on $5,500 a month left over, assessed at 9.00%.
- Monthly income counted$108,000 a year, after tax, divided by twelve.
- $9,000
- Monthly surplus a lender would seeIncome less expenses, commitments and card limits.
- $5,500
- Card limits counted as a repayment3.8% of $0 a month.
- $0
- Assessment rate used6.00% plus a 3.00% buffer.
- 9.00%
- Repayment at the loan rateWhat you would actually pay each month, not the tested figure.
- $4,098
- Rough price guide with your depositStamp duty and fees come out of the deposit, so the real figure is lower.
- $804,000
This is an estimate, not a pre-approval. Every lender counts income, expenses and commitments differently, and the spread between the most and least generous on the panel is often more than $150,000 on the same file. Lending is subject to approval.
Get a real numberEach tool has a page of its own explaining every figure it uses: lmi calculator and borrowing power calculator.
How lenders treat pharmacists
Four ways pharmacists borrow, and what each one meansThe waiver is the part most pharmacists hear about. How a lender reads your pay matters as much, especially when you work in more than one place.
- Lenders mortgage insurance waiver
Tends to suit
Registered pharmacists buying with less than twenty per cent saved
Worth knowing
Commonly up to 90 per cent of the value, some lenders go to 95, and some set a minimum income
- Salaried pharmacist
Tends to suit
Pharmacists employed by a community pharmacy or a hospital
Worth knowing
Usually the simplest to assess, with payslips and an employment contract
- More than one job, or locum shifts
Tends to suit
Pharmacists working across several pharmacies or adding locum work
Worth knowing
Some lenders count income from every job, and others leave a second job out
- Pharmacy owner
Tends to suit
Pharmacists who own all or part of a pharmacy
Worth knowing
Usually assessed on one to two years of tax returns, depending on the lender
You do not need to know which lender counts a second job. Tell us where you work, how you are paid and what you have saved, and we check the panel for you.
Who home loans for pharmacists suit
The pharmacists we check lender policy forLender policy matters most when your deposit is under twenty per cent or your pay comes from more than one place. These are the situations that come up most often.
Pharmacists buying a home with less than twenty per cent saved
Pharmacists working in more than one pharmacy, or adding locum shifts to a main role
Pharmacists whose pay includes weekend and evening penalty rates
Newly registered pharmacists whose income is about to rise
Pharmacy owners and partners whose income shows up as business profit
Pharmacists told by one bank that the insurance premium cannot be avoided
How the process works for pharmacists
Five steps, with your registration and pay checked before step twoWe follow the same five steps as any loan we write. Your registration and every source of income are checked against lender policy before anything is submitted.
Start an application
You send us the basics and we work out what you could borrow and which lenders will look favourably at your situation.
Read this step in full: Start an applicationWhat you need
Income, debts, deposit
Get pre-approved
We put your file to the lender that fits and bring back a pre-approval in writing, subject to lender approval and your circumstances.
Read this step in full: Get pre-approvedWhat we do
Match the lender to your file
Get officially approved
Once your offer is accepted, the lender orders its valuation and issues formal approval.
Read this step in full: Get officially approvedWhat we do
Chase the lender, so you do not have to
Prepare for settlement
We go through the loan documents with you before you sign anything, then coordinate the lender and your settlement agent.
Read this step in full: Prepare for settlementWhat you need
Your questions, asked early
Stay up to date
After settlement we keep the loan under review as rates move and your circumstances change.
Read this step in full: Stay up to dateWhat we do
Review it, and tell you first
Step 1 of 5 · Start an application
About our independent mortgage brokers
The brokers who check a pharmacist's pay against the panelIndependent means no franchise above us and no lender owning a share of the business. Nobody upstairs sets a monthly target, so we can tell you when no waiver applies. Your bank has one pharmacist policy; we compare 40+ lenders.
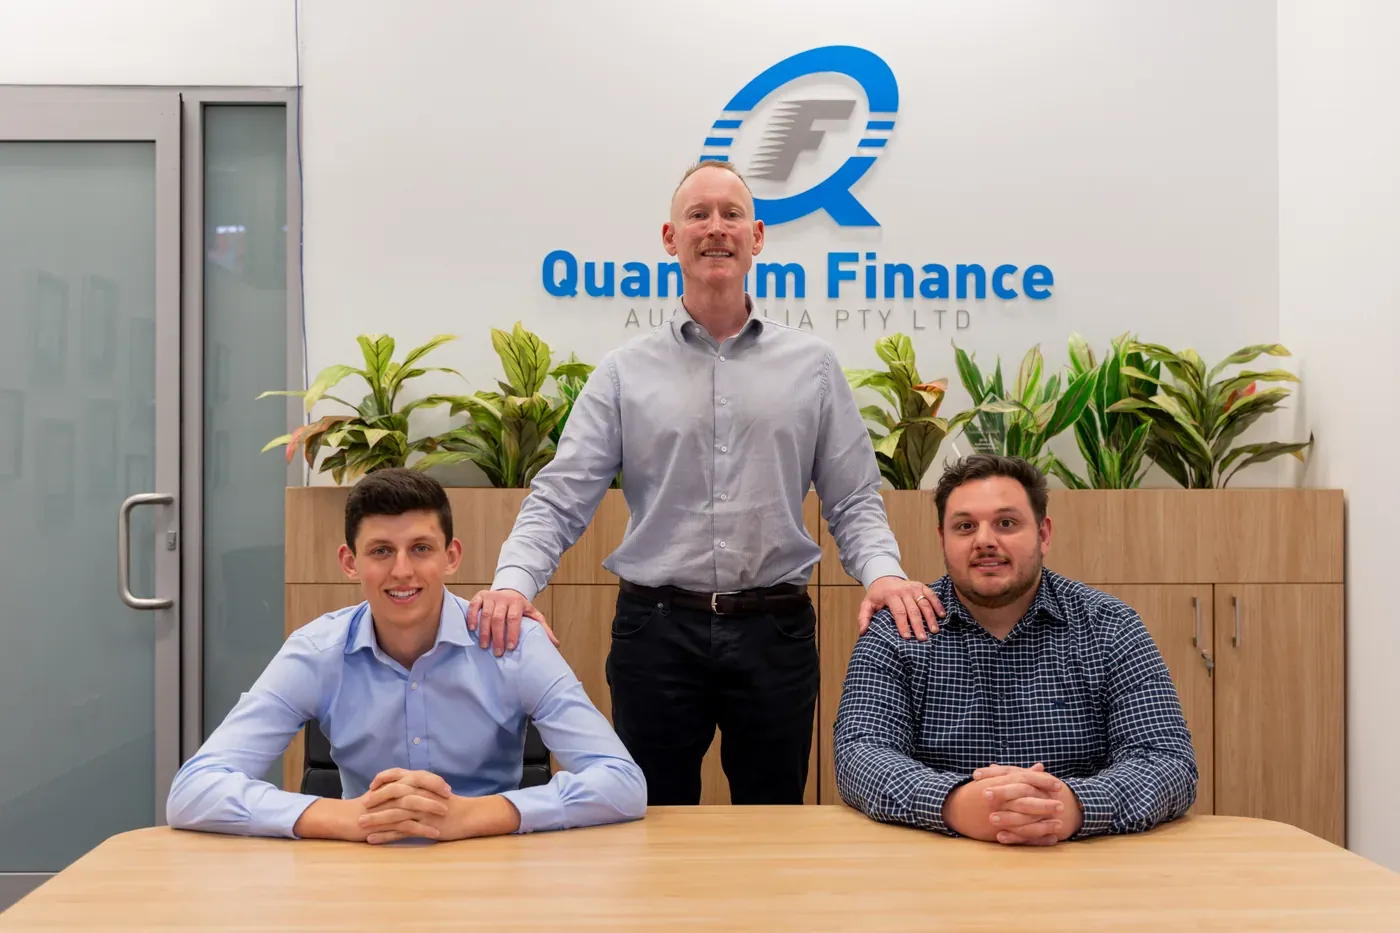
Gavin Harrigan has been broking from West Leederville since 2005. Today it runs on a small team, Gavin Harrigan, Justin Richardson and Xavier Prescott, each with their qualifications on the page. You deal with the person who writes your loan, before settlement and after it.
The work runs from a first home loan, through refinancing and investment lending, out to construction, small developments and commercial property. Same broker, whichever end of that you are at.
- VerifiedBroking since 2005
- VerifiedOver $1 billion in loans settled
- VerifiedAustralian Credit Licence 389083
- VerifiedMoneyQuest accredited
- VerifiedMember of the Finance Brokers Association of Australia (FBAA)
- Verified40+ lenders on the panel
Fifteen minutes is usually enough to tell you where you stand. No cost, no obligation, and any lending is subject to approval and your circumstances.
Why pharmacists choose us
Each lender counts a pharmacist's pay its own way, so somebody should check them allNo franchise and no lender has a say in which loan we recommend to you.
- Included
No franchise, no head office quota
We do not pay a franchise fee, so nobody upstairs sets a monthly target for us to hit. That removes the main reason a broker recommends the wrong loan.
- Included
No lender owns a share of us
The banks have no stake in this business and no claim on where files go. Your bank has one loan to sell you. We do not.
- Included
40+ lenders, one shortlist
We compare 40+ bank and non-bank lenders, then explain why the shortlist looks the way it does. Policy differences decide more applications than rate does.
- Included
We will tell you when the answer is no
If refinancing does not actually save you money, we say so and you leave the loan where it is. A wrong loan costs more than the fee it earns.
- Included
The same broker after settlement
You keep dealing with the person who wrote the loan. We review it as rates and your circumstances change, not once and then never again.
What our clients say
Reviews from people we have written home loans forReviews left by people we have settled home loans for, shown as they wrote them.
Our lender panel for pharmacists
Pharmacist policy is set lender by lender. We compare 40+We work with major banks, smaller banks and lenders that are not banks, and each has its own view of pharmacy income. MoneyQuest gives us access to the panel, and 21+ years of writing home loans tells us where to look first.
A selection of the lenders we are accredited with. Ask us who else is on the panel for your situation.
Our home loan guides
Read one before you talk to a lenderPlain-English answers on borrowing capacity, the WA grant with every figure dated to its source, and what pre-approval is worth. Each one carries a broker's name.
Approvals
Credit scores and home loans
What is on your file, how long it stays there, and what a lender does with it.
Read it: Credit scores and home loans
Borrowing power
How much can I borrow?
Income less commitments, tested at a rate higher than the one you would pay.
Read it: How much can I borrow?
First home buyers
The First Home Owner Grant in WA
Who qualifies, what it is worth, and every figure dated to its WA Government source.
Read it: The First Home Owner Grant in WA
Approvals
Home loan pre-approval, explained
What a lender is actually committing to, and what can still undo it.
Read it: Home loan pre-approval, explained
Meet our Perth mortgage brokers
The broker you talk to is the one who writes your loanWe are a team of three: Gavin Harrigan, Justin Richardson and Xavier Prescott. The person who goes through your payslips is the person who submits the application and the person who reviews it later.
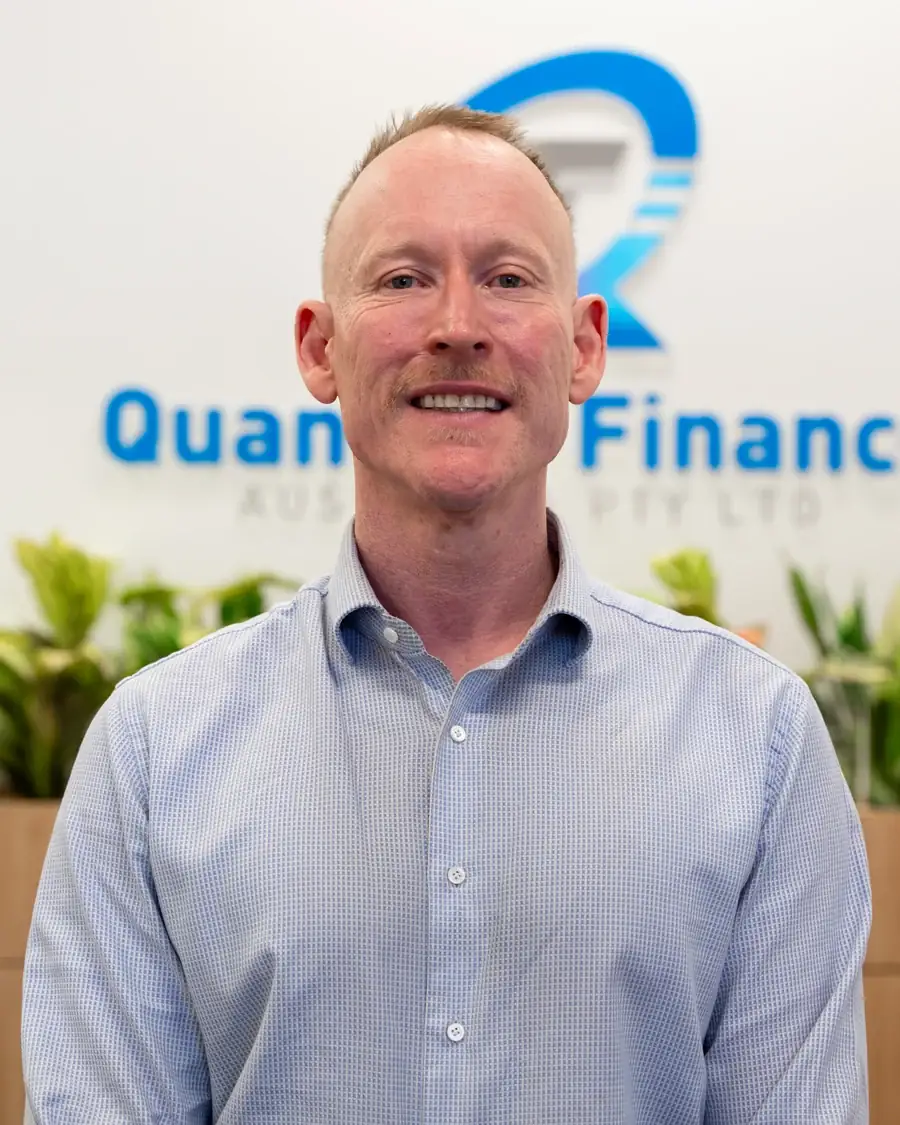
Gavin Harrigan
Managing Director
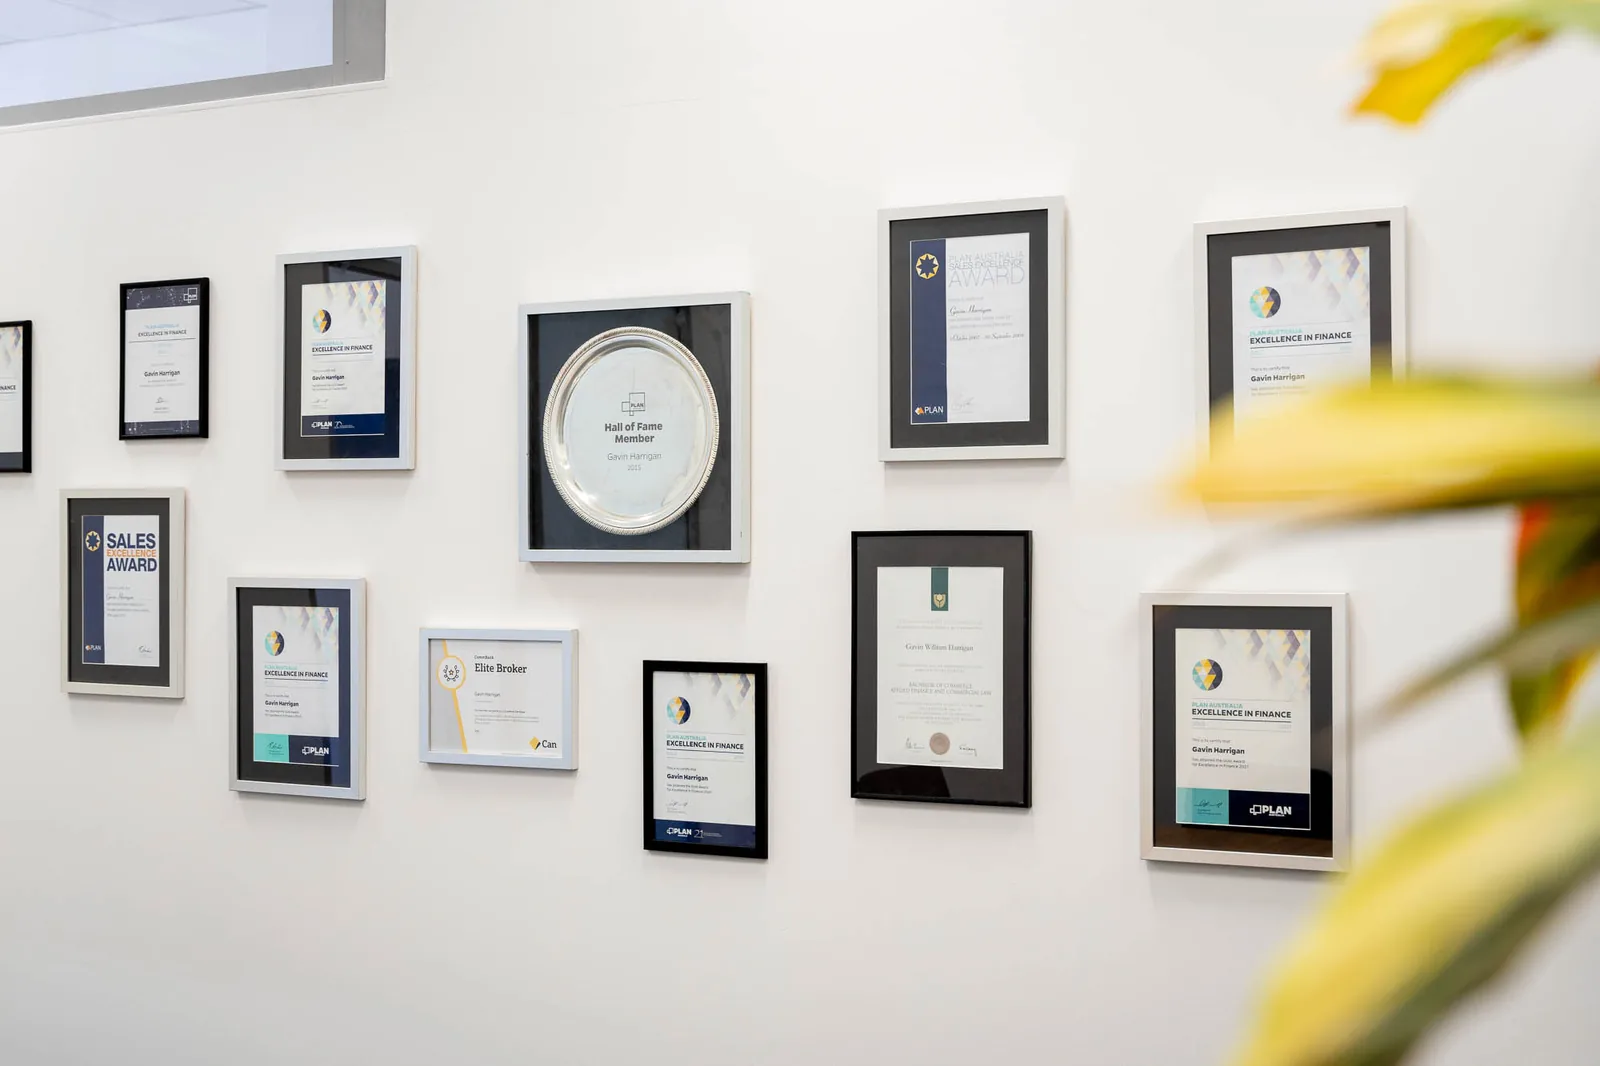
Broking since 2005, four-time Top 100 broker and a PLAN Australia Hall of Fame member.
- Bachelor of Commerce, Applied Finance and Commercial Law, Curtin University
- Diploma of Finance and Mortgage Broking Management, AAMC Training Group
- PLAN Australia Hall of Fame member
- Elite Broker status
- Top 100 Brokers, four times
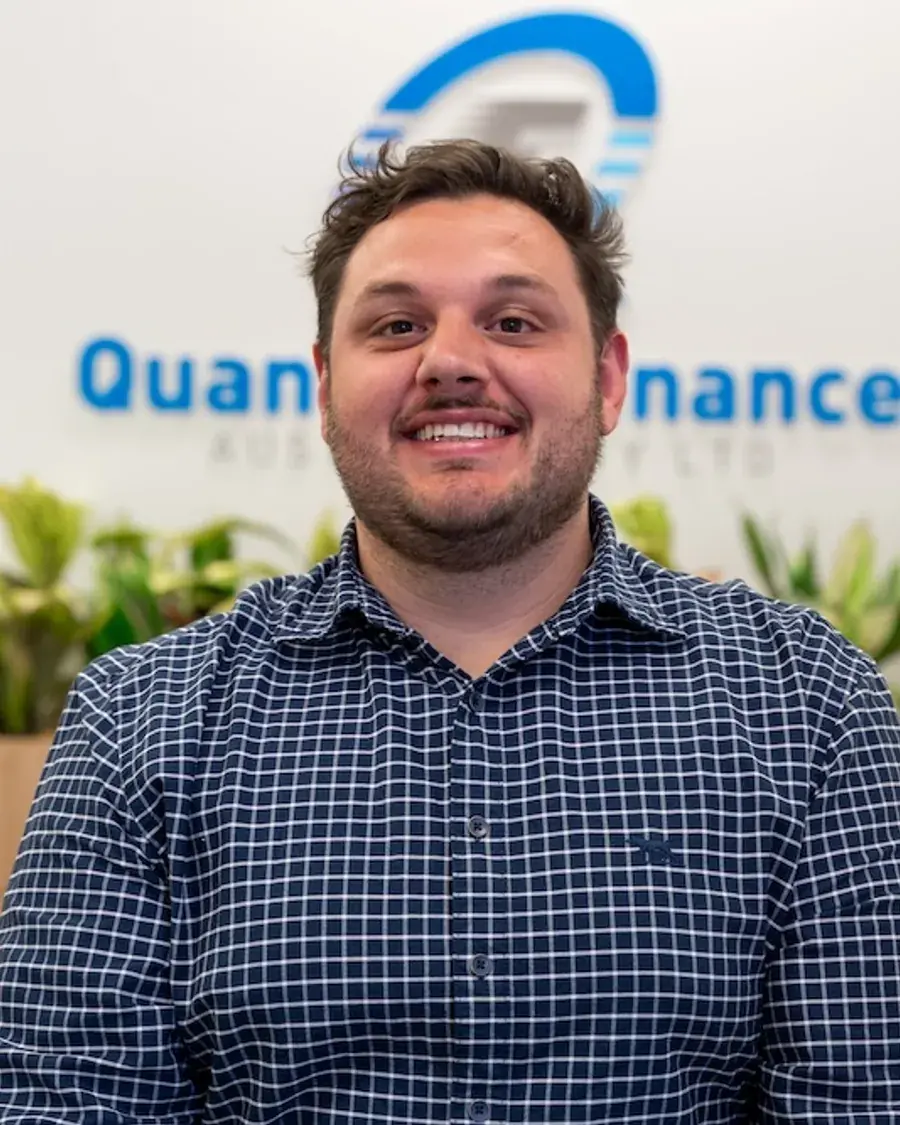
Justin Richardson
Loan Consultant
Business and law background, and a habit of making the process feel simple.
- Bachelor of Commerce, Business Law and Marketing, Curtin University
- Bachelor of Laws (in progress), Murdoch University
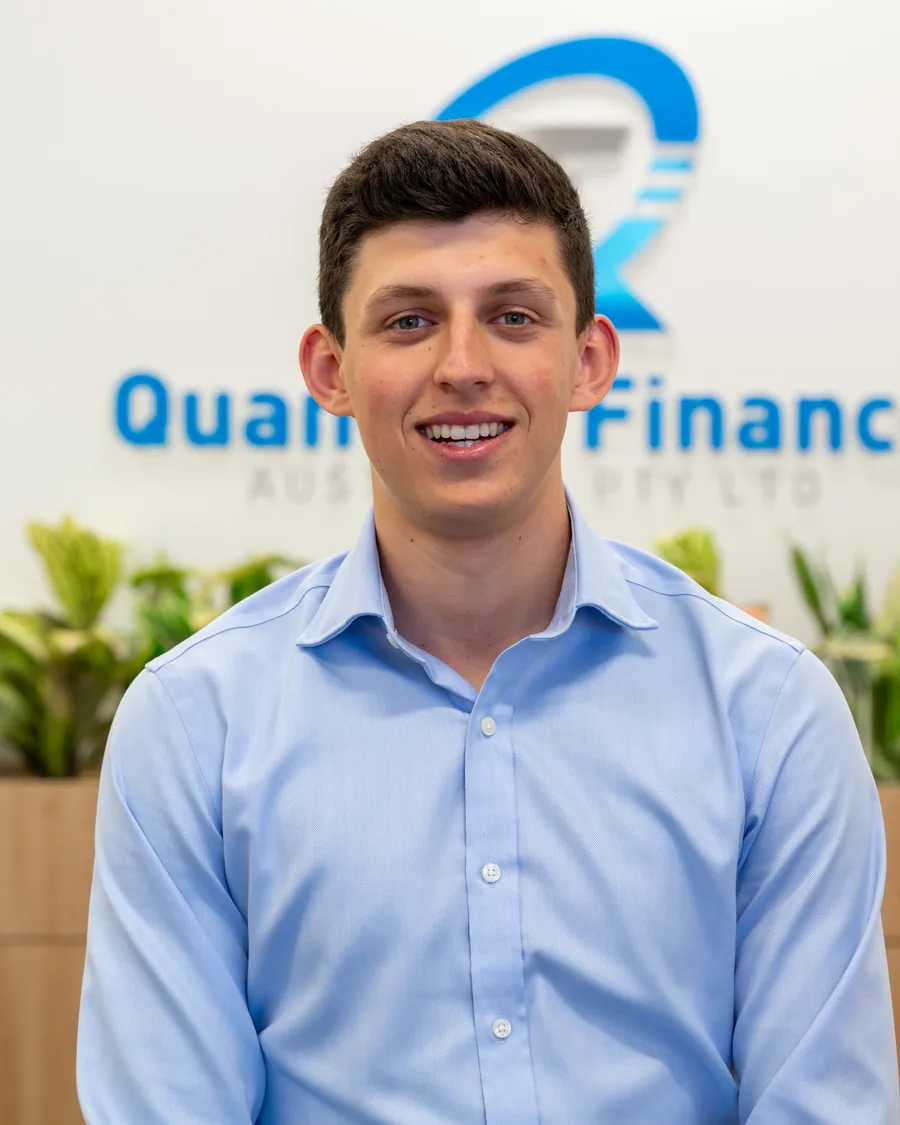
Xavier Prescott
Loan Consultant
Fresh qualifications, a competitor's discipline, and a lot of patience.
- Diploma of Finance and Mortgage Broking Management
Common questions about home loans for pharmacists
Can pharmacists get a home loan without lenders mortgage insurance?
Some lenders waive lenders mortgage insurance for registered pharmacists who have saved less than twenty per cent. The limit is commonly 90 per cent of the property's value, and some lenders go to 95. Any loan is subject to lender approval and your circumstances.
What do I need to qualify as a pharmacist?
Usually current registration as a pharmacist with AHPRA, the national agency that registers health practitioners, and income that covers the repayments. Some lenders also set a minimum income. We check your registration and pay against each lender.
Will a lender count my second job or locum shifts?
It depends on the lender. Some count income from every pharmacy you work in, and others leave a second job out. Locum work billed through an ABN, an Australian Business Number, is usually assessed like self-employed income.
I have just registered. Can I still apply?
Yes, and lenders differ on how they treat newly registered pharmacists. Some are more flexible than others, so we check your registration status and employment contract against the panel before you apply.
I own a pharmacy. How is my income assessed?
Usually as self-employed income, on one or two years of tax returns depending on the lender. We look at what the pharmacy pays you and how the business is set up. Then we match you to lenders whose rules fit.
Will I get a lower interest rate as a pharmacist?
Not automatically. A loan with a waiver can carry a higher rate or fees, especially at 90 per cent or more of the property's value. We compare the whole loan across the panel for your situation before we quote you a rate.
Related home loans we arrange
Other home loans pharmacists ask us aboutMany loans involve more than one of these. If yours does, it is the same broker and the same conversation.
Home Loans by Occupation
Lender policies that recognise your occupation, starting with the insurance waiver.
Learn moreabout Home Loans by Occupation
Low Deposit Home Loans
Buying with less than twenty per cent saved, with every route costed first.
Learn moreabout Low Deposit Home Loans
First Home Buyer Loans
Your first place in Perth, from what you can borrow through to the keys.
Learn moreabout First Home Buyer Loans
The information on this page is general in nature and does not take into account your objectives, financial situation or needs. Any figures shown are estimates only. Lending is subject to approval, and to the lender's terms, conditions, fees and charges. Consider whether the information is appropriate for you before acting on it.
Get in touch
Talk to us about your pharmacy income and your loanFill in a few details and you are done. A broker reads them, checks your situation against the panel, and rings you back on the number you give us.
Would rather just talk?
Ringing is quicker than waiting for us to ring you, and you get a broker rather than a queue.
1300 813 113